
WASHINGTON — In response to the persistent and debilitating drought conditions plaguing vast stretches of the United States, the Internal Revenue Service (IRS) has officially issued comprehensive guidelines granting a vital extension of tax relief. Designed specifically for agricultural producers who have been forced by extreme weather to sell or exchange their livestock prematurely, the new framework provides much-needed financial breathing room.
The directive allows eligible farmers and ranchers significantly more time to replace their herds and legally defer the payment of capital gains taxes on the proceeds from these forced sales. As climate pressures mount across North America, this federal intervention serves as a critical economic buffer for a sector facing unprecedented environmental headwinds.
Main Facts: Relief, Rules, and Requirements
The cornerstone of this recent administrative action is the official IRS guidance—referenced in recent advisory documents—which outlines the geographical areas, eligibility criteria, and operational mechanics of the tax postponement.
What the Tax Relief Entails
Under normal circumstances, agricultural producers who realize capital gains from selling livestock in numbers exceeding their typical operational patterns must report those gains on their federal income tax returns for the year of the sale. However, federal tax code provisions allow for the deferral of these taxes if the proceeds are reinvested in replacement livestock within a specified timeframe.
The new IRS guidance extends this replacement window. Instead of the standard two-year period, affected producers generally receive a four-year window to acquire replacement animals. Furthermore, if drought conditions persist, the IRS is authorized to extend this period even further.
Eligible Livestock and Exclusions
It is important to note that this tax relief is not a blanket exemption for all agricultural sales. The provisions specifically target:
- Draft, Breeding, or Dairy Animals: Livestock kept strictly for operational continuity, milk production, or breeding purposes qualify for the tax deferral.
- Exclusions: Livestock raised strictly for slaughter, sporting purposes, or non-breeding commercial meat production do not meet the primary criteria for this specific climate-induced exception.
Producers must conclusively demonstrate that the sale or exchange of their livestock was directly caused by the severe environmental conditions plaguing their specific geographic region, and that their county or district received federal recognition or categorization for drought impact.
Chronology of the Crisis: Escalating Aridity Across America
To understand the necessity of the IRS’s intervention, one must examine the timeline of escalating aridity that has gripped the United States over recent years.
The Escalation of Mega-Droughts
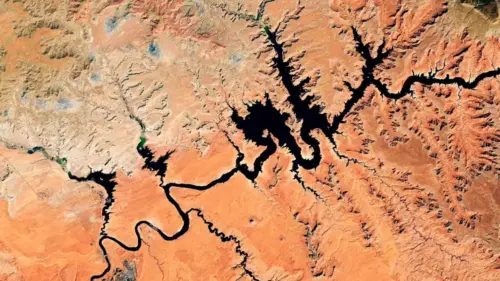
For well over a decade, scientists and agricultural economists have documented a structural shift in North American climate patterns. Driven by complex atmospheric phenomena—including persistent La Niña cycles, marine heatwaves, and shifting jet streams—large swaths of the American West, the Great Plains, the Southwest, and parts of the Midwest have suffered from consecutive years of below-average precipitation.
The Trigger Point for Emergency Sales
By the spring and summer planting and grazing seasons, soil moisture levels frequently plummet to historic lows. Pastures and rangelands, which typically provide cost-effective, natural forage for cattle, sheep, and other livestock, turn to dust.
Ranchers face an agonizing economic choice:
- Purchase expensive supplemental feed: With grain and hay prices soaring due to regional crop failures, buying feed often becomes financially unsustainable.
- Liquidate the herd: Selling off foundational breeding stock becomes the only viable path to prevent catastrophic financial ruin.
The Federal Response Timeline
Recognizing that premature liquidations threaten the long-term viability of the nation’s food supply chain, federal agencies coordinate annually to track these meteorological markers. The National Drought Mitigation Center (NDMC) continuously monitors precipitation, streamflow, and soil conditions.
When counties cross specific thresholds into severe, extreme, or exceptional drought, they are flagged for federal assistance. The IRS then utilizes this data to publish updated administrative notices—such as the recent Notice framework—ensuring that tax policy adapts in real time to ongoing climatic realities.
Supporting Data: The Scope of the Affected Regions
The administrative reach of the recent IRS guidance is vast, reflecting the nationwide footprint of contemporary dry spells.
Geographic Coverage
According to federal disclosures, the current relief framework encompasses an unprecedented operational zone:
- 49 U.S. States: Nearly the entire continental United States has experienced pockets of qualifying drought severity within the designated monitoring windows.
- Territories and Districts: The District of Columbia and Puerto Rico are included alongside specific outlying agricultural zones that reported extreme weather anomalies during the assessment periods.
The Mechanics of the Replacement Window
To appreciate the data-driven relief, consider how the calendar operates under IRS Notice guidelines:
- The Four-Year Baseline: When producers sell excess livestock due to drought in an eligible federal disaster area, the clock starts on a standard four-year replacement window.
- The "Drought-Free Year" Trigger: If the drought persists into the fourth year, the replacement period is automatically extended. It continues to roll forward until the end of the producer’s taxable year that follows the first "drought-free year."
- Defining a Drought-Free Year: A drought-free year is defined as a 12-month period ending on August 31 during which the affected county (or any contiguous county) has not reported severe, extreme, or exceptional drought conditions in any single weekly report.
If the period between September 1 and August 31 passes entirely without a severe drought classification in the designated zones, that cycle officially qualifies as the first drought-free year, setting the final deadline for tax compliance and herd replacement at the conclusion of the following fiscal year.
Official Responses and Perspectives
The announcement has drawn widespread commentary from agricultural stakeholders, federal officials, and economic analysts who view the policy as an essential lifeline for rural communities.
Perspectives from Federal Leadership
Representatives from the Department of the Treasury and the IRS have emphasized that tax administration must remain responsive to natural disasters. Executive leadership within the agency noted that while tax collection is vital for public infrastructure, penalizing farmers for weather events entirely outside their control undermines national economic stability. By streamlining the deferral process, the federal government aims to keep generational ranches solvent.
Industry and Agricultural Associations
National and regional cattlemen’s associations, farm bureaus, and agricultural cooperatives have broadly welcomed the guidance, though many reiterate that policy must be matched by long-term investments in water management and soil conservation.
"When a rancher is forced to sell a prize-winning breeding herd built over thirty years because grass won’t grow, they aren’t generating a profit—they are managing a tragedy," stated a spokesperson for a prominent Western livestock association. "Allowing them to defer the tax burden on those emergency liquidation funds ensures they have the capital necessary to rebuild when the rains finally return."
Agricultural economists point out that without these extensions, producers would face a dual crisis: the immediate loss of livestock revenue followed immediately by a crippling tax bill on phantom "gains" that were actually emergency distress sales.
Implications for the Future of American Agriculture
The implementation of these extended tax deferrals carries profound implications for the future structure, economic resilience, and operational strategy of the U.S. agricultural sector.
Preventing Permanent Industry Shrinkage
The most immediate implication is the prevention of permanent contraction in the livestock inventory. When herds are liquidated en masse and not replaced, meat processing infrastructure, regional feed suppliers, and rural economies suffer long-term structural damage. By giving producers up to four years—and potentially longer—to restock, the IRS helps stabilize the domestic supply chain for beef, dairy, and other livestock products, mitigating inflationary pressures on consumer food prices down the road.
Adaptation to Climate Volatility
As weather patterns become increasingly erratic, the interface between tax policy and climate adaptation is tightening. The reliance on retrospective disaster declarations highlights the need for predictive, proactive economic safety nets. Farmers and ranchers are increasingly investing in drought-resistant pastures, rotational grazing techniques, and advanced water-harvesting infrastructure. However, these transitions require capital—capital that would otherwise be depleted by premature tax liabilities on forced livestock sales.
A Model for Fiscal Flexibility
Economists suggest that the IRS’s handling of drought-related livestock sales could serve as a blueprint for other sectors facing climate-induced disruptions. Flexibility in tax timing acknowledges that traditional fiscal calendars do not always align with the chaotic realities of ecological cycles.
Conclusion
Ultimately, the IRS’s extended tax relief guidelines represent much more than a routine administrative adjustment. For thousands of American farmers and ranchers gazing out over parched pastures and empty feedlots, this policy provides a crucial window of financial survival. By bridging the gap between an environmental disaster and economic recovery, the federal framework helps ensure that the stewards of the nation’s agricultural lands can weather the storm—and live to farm another day.

Leave a Reply