
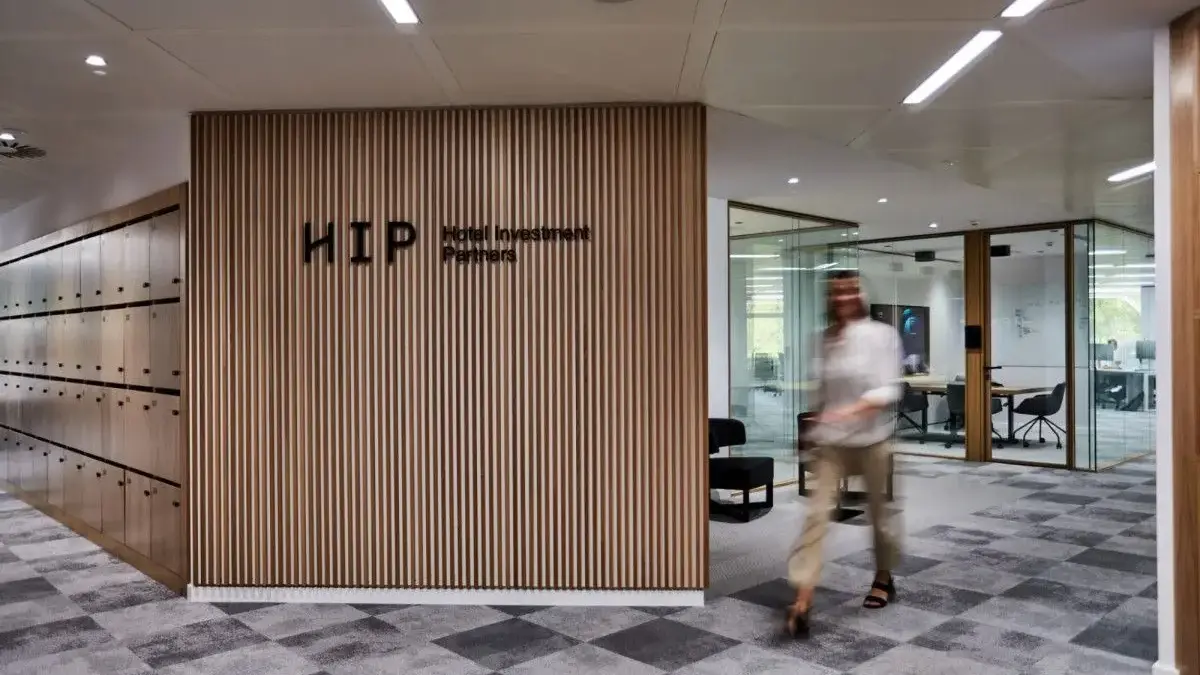
FINANCIAL MARKETS / REAL ESTATE — In a strategic pivot driven by persisting macroeconomic headwinds and global market turbulence, American private equity titan Blackstone has decided to postpone the highly anticipated initial public offering (IPO) of Hotel Investment Partners (HIP). Originally slated for a late October or early November debut on the stock exchange, the flotation has now been pushed back, with financial and real estate insiders pointing toward early 2027 as the most viable window for the market debut.
Despite the operational readiness of the platform and the underlying interest from institutional investors, the decision underscores a cautious approach by major alternative asset managers navigating a complex landscape defined by shifting interest rates, persistent inflation, and geopolitical instability.
1. Main Facts: The Anatomy of the Postponement
The core of the transaction remains fully mapped out, yet the timing has shifted significantly. Blackstone—the world’s largest alternative asset manager—had orchestrated the groundwork to launch HIP, the premier hotel investment vehicle in Southern Europe, onto the public markets.
According to financial sources cited by specialized media, the underwriting syndicate and financial advisors working on the deal concluded that while underlying investor demand does exist, the current macroeconomic and market volatility fails to guarantee the stable conditions necessary for a successful, high-valuation debut.
Key Transaction Parameters:
- Target Capital Raising: Blackstone aims to secure approximately €700 million through a primary offering, structured as a Public Subscription Offering (OPS). This capital injection is earmarked to fuel the ongoing expansion and acquisition strategy of the hospitality portfolio.
- Secondary Offering: The primary raise could potentially be supplemented by a secondary offering (OPV) involving the sale of existing shares by current stakeholders.
- Underwriting Syndicate: A powerhouse consortium of international and domestic financial institutions is orchestrating the placement. Santander, Morgan Stanley, Citi, BNP Paribas, and Goldman Sachs are acting as global coordinators and joint bookrunners. They are supported by a second tier of major institutions including Bank of America, Crédit Agricole, and Société Générale, alongside other international lenders.
- Regulatory Readiness: The structural documentation, prospectuses, and preliminary filings are understood to be practically finalized. The advisory syndicate reportedly has the paperwork ready to be formally submitted to Spain’s National Securities Market Commission (CNMV), though bankers have strongly advised holding off until volatility subsides.
2. Chronology of the Deal: From Summer Optimism to a 2027 Horizon
The journey toward bringing HIP to the public markets has been characterized by careful calibration, shifting timetables, and acute sensitivity to European macroeconomic indicators.
- Spring–Summer 2024: Whispers and initial reports began to circulate in financial circles regarding Blackstone’s intention to monetize or provide liquidity for its massive Southern European hospitality asset. Given the post-pandemic boom in Mediterranean tourism, analysts identified an open window for high-performing leisure real estate.
- September 2024: Planning accelerated rapidly. Investment banks were formally mandated, and the structuring of the IPO took shape, with initial internal targets pointing toward a late autumn window (specifically October or November 2024) to capture investor attention before the end-of-year holiday slowdown.
- October 2024: As the final preparatory stages were completed—including audits, portfolio valuations, and regulatory drafts—global market conditions began to deteriorate. A spike in long-term bond yields, combined with escalating geopolitical tensions in the Middle East and mixed inflation prints in the United States and Europe, cast a pall over European equity capital markets (ECM).
- Late October 2024 (The Pivot): Following consultations between Blackstone executives and the lead coordinators (Santander, Morgan Stanley, Citi, BNP, and Goldman Sachs), the consensus shifted decisively. Recognizing that pricing a multi-million euro real estate investment trust (REIT-style vehicle) in a jittery market risked undervaluing the asset, the decision was made to halt the immediate push.
- Current Status (Looking Ahead to 2027): The timeline has been formally recalibrated. While the IPO has not been canceled—but merely deferred—market participants now look past 2025 and 2026, targeting early 2027 as the realistic horizon when monetary easing cycles and macroeconomic stability might create a more hospitable climate for large-cap real estate listings.
3. Supporting Data: The Scale and Footprint of Hotel Investment Partners (HIP)
To understand the magnitude of the postponed IPO, one must examine the sheer scale of Hotel Investment Partners. Founded in 2015 and acquired by Blackstone in 2017 (with subsequent bolt-on acquisitions, notably buying control of Hotelbeds’ real estate arm and consolidating assets from Sabadell and other Spanish institutions), HIP has grown into the undisputed heavyweight of Mediterranean leisure hotel real estate.
Portfolio Overview:
- Geographic Reach: The portfolio spans four core Southern European destinations: Spain, Portugal, Italy, and Greece. These markets represent the epicenter of European leisure and sun-and-beach tourism.
- Asset Count: A robust portfolio comprising 62 high-end resort and urban hotels.
- Room Capacity: Approximately 20,000 hotel rooms under ownership.
- Operational Partnerships: HIP does not manage hotels directly; instead, it acts as an institutional asset owner that partners with the world’s most prestigious hospitality operators to run the properties. Its tenant and operator roster reads as a "Who’s Who" of global hospitality, featuring brands such as Hyatt, Barceló Hotel Group, Meliá Hotels International, and Marriott International.
Macroeconomic Tailwinds vs. Financial Headwinds:
The irony of the postponement lies in the disconnect between operational performance and financial market conditions. On the ground, HIP’s hotels have enjoyed record-breaking occupancy rates and average daily rates (ADR) driven by an insatiable post-pandemic travel boom across Southern Europe.
However, real estate valuations are intrinsically tied to the cost of capital. The underlying fundamentals of the tourism sector remain exceptionally strong, but the mechanics of public market pricing require favorable yield spreads—conditions currently constrained by external economic pressures.
4. Official Responses and Market Analysis: Why the Deal Was Shelved
Financial analysts and market commentators have pointed to a convergence of macroeconomic factors that forced Blackstone’s hand. While private equity firms are notoriously resilient and capable of holding assets through private vehicles indefinitely, public listings require exact timing to maximize valuation multiples.
The Deciding Factors:
-
The Cost of Debt and Long-Term Interest Rates:
Although central banks (including the European Central Bank) have begun cautious monetary easing cycles, long-term bond yields remain volatile. Real estate investment vehicles rely heavily on debt financing for acquisitions and capital expenditure. Higher long-term interest rates increase the hurdle rate for investors, compressing asset valuations across the commercial and hospitality real estate sectors. -
The Rise of Alternative Risk-Free Yields:
The repricing of fixed-income assets means that institutional investors—pension funds, sovereign wealth funds, and insurance companies—can secure attractive, predictable returns from sovereign debt (such as Spanish, Italian, or German government bonds) without taking on equity or real estate risk. Consequently, equity risk premiums for new IPOs must be exceptionally compelling to draw capital away from risk-free instruments. -
Geopolitical Volatility and Macro Uncertainty:
Persistent conflicts in the Middle East and Eastern Europe, combined with electoral cycles and shifting trade policies in major global economies, have created an unpredictable trading environment. Equity capital markets are notoriously intolerant of uncertainty; sudden risk-off sentiment can derail an offering during the critical book-building phase. -
Inflationary Pressures:
While inflation has retreated from its post-pandemic peaks, input costs—including labor, energy, food, and property refurbishment materials—remain elevated. These factors impact operational margins at the hotel level, introducing variables that equity analysts scrutinize meticulously when evaluating initial public offerings.
Despite these hurdles, financial advisors close to the dossier emphasize that the choice to wait is entirely optional. Blackstone is under no financial distress to liquidate or float the asset prematurely; its private equity model allows it to collect robust cash flows from HIP’s operations while waiting for public market valuations to align with its internal asset appraisals.
5. Implications: What This Means for the European Hospitality and Real Estate Sectors
The postponement of the HIP IPO carries significant signaling value for the broader European real estate and tourism investment ecosystem.
Broader Industry Takeaways:
-
The IPO Window Remains Narrow:
For months, investment bankers have predicted a broad revival of the European IPO market. The delay of one of the year’s most anticipated real estate flotations demonstrates that institutional investors and sponsors remain highly selective. Secondary and primary listings cannot force their way through choppy markets simply on the strength of brand name and operational scale. -
Private Equity Holding Periods Are Extending:
Blackstone’s decision illustrates a broader trend across private markets: sponsors are increasingly willing to hold trophy assets longer within private funds, utilizing dividend recapitalizations, minority stake sales, or bolt-on acquisitions to generate liquidity and growth rather than rushing into public listings that risk suboptimal valuations. -
Southern European Leisure Resiliency:
Despite the financial delay, the underlying thesis for Mediterranean tourism real estate remains exceptionally bullish. The fact that Blackstone continues to plan for a future multi-million euro capital raise—aimed specifically at expanding the portfolio—signals unwavering confidence in the long-term structural demand for leisure travel in Spain, Portugal, Italy, and Greece. -
M&A as an Alternative Path:
While the public markets digest macroeconomic volatility, institutional interest in prime European hotel portfolios is unlikely to wane. Private M&A, club deals, and secondary transactions between institutional funds may well serve as the preferred liquidity channel for hospitality assets in the interim.
Conclusion
Blackstone’s decision to defer the Hotel Investment Partners IPO to early 2027 is a masterclass in disciplined capital stewardship. By prioritizing valuation integrity over arbitrary timelines, the private equity giant has ensured that when HIP eventually steps onto the public stage, it will do so from a position of undeniable strength—backed by 62 premier properties, 20,000 rooms, and a robust balance sheet insulated from short-term market noise. Until then, Europe’s largest hotel landlord will continue to reap the rewards of a booming Mediterranean tourism market from the stability of the private sphere.

Leave a Reply