
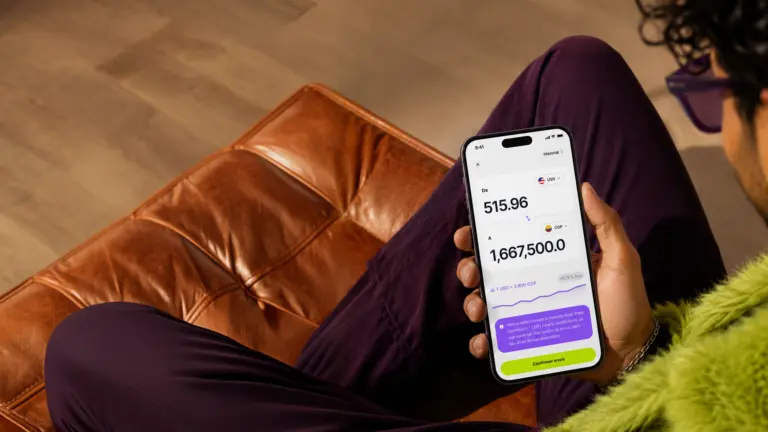
BARRANQUILLA, COLOMBIA — In a move that signals the ongoing decentralization of Colombia’s booming financial technology sector away from traditional hubs like Bogotá and Medellín, a new startup called Monni has officially announced its entry into the market. Headquartered on the Caribbean coast in Barranquilla, Monni is introducing a comprehensive multi-currency digital wallet designed to allow both individuals and businesses to manage US dollars, euros, Colombian pesos, and Mexican pesos from a single, unified application.
The platform, which has officially opened its waiting list for prospective users and corporate clients, aims to solve a persistent friction point in the modern economy: the cumbersome fragmentation of managing international money across multiple legacy systems, high-fee traditional wire services, and siloed digital accounts. By blending multi-currency balance management, instant currency conversion, and an international debit card linked directly to the account, Monni is positioning itself as a comprehensive paytech solution for a rising demographic of borderless earners.
Main Facts: What is Monni and How Does It Work?
At its core, Monni is engineered to bridge the gap between local financial ecosystems and global commerce. Founded in 2025, the startup addresses the operational complexities faced by freelancers, digital nomads, remote workers, and cross-border enterprises who routinely earn, hold, and spend money in foreign currencies.
The Initial Currency Suite
During its initial rollout phase, Monni will support four key currencies:
- US Dollar (USD)
- Euro (EUR)
- Colombian Peso (COP)
- Mexican Peso (MXN)
By consolidating these diverse funds into a single ecosystem, Monni eliminates the necessity for users to jump between different applications or maintain multiple traditional bank accounts just to execute everyday international transactions.
Core Product Offerings
- Unified Digital Wallet: Users can view, monitor, and maintain balances in USD, EUR, COP, and MXN simultaneously within an intuitive mobile and desktop interface.
- Seamless In-App Conversions: The platform provides native currency conversion capabilities, bypassing the protracted processing times and opaque exchange rates typically imposed by legacy correspondent banking networks.
- International Debit Card: Monni is coupling its digital balances with a physical and virtual international debit card, allowing users to spend their multi-currency funds globally wherever major payment networks are accepted.
- Global Transfers: The platform integrates streamlined infrastructure designed for sending and receiving international wires and peer-to-peer payments with lower friction and enhanced transparency.
- Enterprise Solutions: Moving beyond retail consumers, Monni features a robust corporate tier equipped with granular role-based permissions, allowing finance and administrative teams to collaboratively manage company funds, disburse payroll, and handle vendor payments across borders.
Chronology of Development and Strategic Roadmap
Monni’s journey from conception to market entry reflects the fast-paced evolution of Latin America’s fintech landscape.
- Early 2025 (Foundation): Monni is officially established in Barranquilla, Colombia, by a founding team recognizing the underserved needs of Caribbean and coastal Colombian businesses operating in international trade and digital services.
- Late 2025 / Early 2026 (Product Architecture & Beta Testing): The company develops its core multi-currency ledger and secures foundational partnerships required to issue international payment credentials and handle multi-jurisdictional compliance.
- Current Phase (Waiting List Launch): Monni initiates its public debut in Colombia by opening an exclusive waiting list for individual users, freelancers, and businesses eager to test the platform prior to its general availability.
- Third Quarter of 2027 (Future Product Expansion): According to the company’s strategic roadmap, Monni plans to expand its financial product suite by introducing an integrated credit card option, though this product remains outside the scope of the initial launch phase.
Supporting Data and Market Context
Monni enters a vibrant and rapidly maturing Colombian fintech ecosystem. According to data from industry groups like Latam Fintech Hub, Monni occupies a vital niche within the paytech (payment technology) segment, which has seen exponential growth over the past half-decade.
The Rise of the Borderless Workforce
Colombia has rapidly cemented its status as a regional powerhouse for remote work and digital nomadism. Cities like Medellín, Bogotá, and Barranquilla host tens of thousands of remote professionals working for international technology firms, marketing agencies, and consultancies. These workers face unique financial hurdles:
- Receiving US dollars or euros typically incurs high wire transfer fees (often ranging from $15 to $50 per transaction).
- Traditional commercial banks in Colombia impose strict bureaucratic requirements and unfavorable exchange rates when converting incoming foreign currency into Colombian pesos.
- Many digital nomads prefer to retain a portion of their earnings in hard currencies (like USD or EUR) as a hedge against local currency volatility and inflation, a need that traditional Colombian savings accounts fail to satisfy natively.
Regional Decentralization
Historically, the vast majority of Colombian fintech startups—such as neobanking giants and payment gateways—have chosen to base their headquarters in Bogotá or Medellín. By establishing its roots in Barranquilla, Monni highlights the growing economic dynamism of Colombia’s Caribbean coast. Barranquilla serves as a historic port city and a vital commercial gateway for international trade, making it a strategic and culturally symbolic home base for a company focused on cross-border financial fluidity.
Leadership and Official Perspectives
The strategic vision behind Monni is driven by a seasoned leadership team with deep expertise in technology and financial systems.
- Roberto De Las Salas (CEO): As Chief Executive Officer, De Las Salas has spearheaded the company’s strategic direction, positioning Monni not merely as another digital wallet, but as an indispensable financial infrastructure layer for Latin America’s new wave of global workers. Industry observers note that his leadership emphasizes operational resilience, compliance, and user-centric product design.
- Ciro Herrera (Co-founder & CTO): As Chief Technology Officer, Herrera oversees the engineering and security architecture of the platform. Building a multi-currency ledger that complies with diverse regulatory frameworks while maintaining lightning-fast transaction speeds is a formidable technical challenge—one that Herrera and his engineering team have tackled by deploying modern cloud-native infrastructure and robust API integrations.
While specific regulatory disclosures and exact fee schedules will be rolled out progressively as the platform transitions from its waiting list phase to full public deployment, company executives have emphasized that transparency and cost-efficiency will form the cornerstone of Monni’s value proposition.
Broader Implications for the Colombian Financial Landscape
The introduction of Monni carries profound implications for both consumers and traditional financial institutions in Colombia.
1. Disrupting the Oligopoly of Traditional Remittances and FX
For decades, cross-border currency exchange in Colombia has been heavily dominated by traditional commercial banks and legacy remittance operators. These institutions have traditionally profited from wide spreads (the difference between the buy and sell price of a currency) and high flat-fee structures. By offering a digital-native, multi-currency alternative where users can store and convert funds dynamically, Monni exerts downward pressure on market pricing, forcing legacy players to modernize or lose market share.
2. Empowering Small and Medium Enterprises (SMEs)
While individual freelancers stand to gain immediate convenience, the inclusion of multi-user corporate accounts is expected to be a game-changer for Colombian SMEs engaged in international trade, import/export, or outsourcing. Small businesses often struggle to manage foreign currency invoices or pay international software subscriptions using standard Colombian corporate debit cards, which frequently encounter blocks, high international purchase taxes, or unfavorable conversion rates. Monni’s enterprise tier—complete with role-based permissions—democratizes treasury management tools that were once exclusively available to large multinational corporations.
3. Financial Inclusion and Global Integration
By making it easier to hold hard currencies like US dollars and euros, Monni provides a practical financial buffer for citizens navigating macroeconomic fluctuations. Furthermore, it integrates Colombian talent more seamlessly into the global digital economy, reducing the friction of getting paid from abroad and allowing local professionals to manage their global earnings with unprecedented autonomy.
Conclusion and Outlook
As Monni opens its initial waiting list in Colombia, the fintech community will be watching closely to see how the Barranquilla startup executes its ambitious roadmap. By combining multi-currency capabilities (USD, EUR, COP, MXN) with a sleek mobile interface, an international debit card, and tailored enterprise tools, Monni is addressing real, acute pain points in the modern Latin American economy.
While the definitive testing ground—full public deployment—lies ahead, and long-term milestones such as the 2027 credit card rollout remain on the horizon, Monni’s arrival underscores an undeniable reality: the future of finance in Colombia is borderless, multi-currency, and increasingly decentralized. Interested users and businesses can currently register for the waiting list via the company’s official channels as preparations ramp up for its official market rollout.

Leave a Reply