
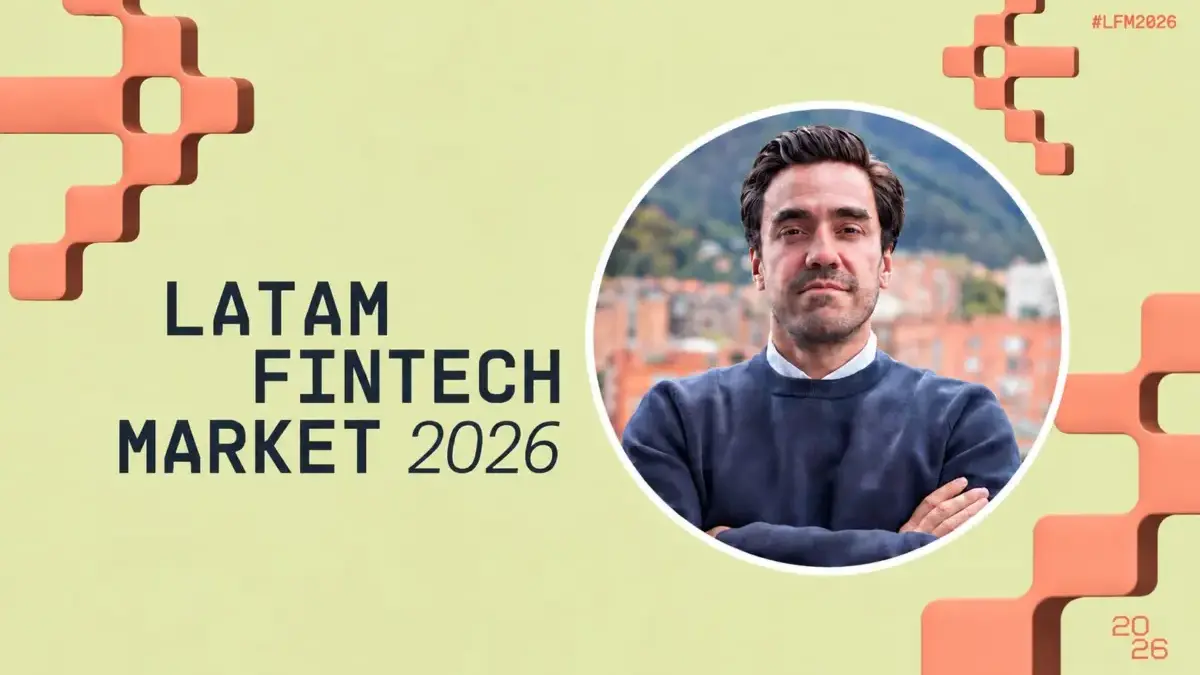
BARRANQUILLA — The future of digital payments, the persistent burden of financial transaction taxes, and the structural overhaul of credit access took center stage during the Latam Fintech Market 2026, held on September 17 and 18 in Barranquilla. Amid a rapidly evolving economic ecosystem, Colombia Fintech—the country’s premier industry association—delivered a sharp, forward-looking manifesto to the national government.
The organization’s executive president, Gabriel Santos, used the high-profile platform to urge the administration to phase out the controversial 4×1,000 financial movement tax, scale up the Bre-B immediate payment system by removing artificial caps, and rewrite lending methodologies to combat informal predatory lending. While discussions between the industry and the executive branch have been characterized as constructive, the proposals highlight a looming tension between fostering digital innovation and maintaining fiscal stability.
Main Facts
The 2026 edition of the Latam Fintech Market brought together regional regulators, institutional leaders, and technology pioneers to debate the next generation of financial services in Colombia. The core proposals and developments emerging from the summit include:
- The 4×1,000 Tax Phase-Out: Colombia Fintech formally requested a gradual and progressive dismantling of the financial transactions tax (gravamen a los movimientos financieros), which Santos labeled a "barbarity." While political and legislative momentum exists, a concrete timeline, reduction schedule, and fiscal compensation strategy have yet to be established.
- Expansion of Bre-B: The association called for the immediate payment infrastructure, Bre-B, to enter its next evolutionary phase. This includes raising or eliminating transaction caps currently restricted by financial institutions, integrating state disbursements (such as public payrolls and subsidies), and streamlining point-of-sale experiences.
- Regulatory Evolution and New Entrants: Bolstered by the Superintendencia Financiera’s recent authorization of Revolut Bank Colombia on August 31, 2026, fintech leaders argue that heightened market competition will naturally drive economic growth and expand state tax revenues without imposing punitive burdens on existing firms.
- Combating Informal Credit: With micro, small, and medium-sized enterprises (MSMEs) and everyday citizens facing steep financial exclusion, the industry proposed reforming interest rate caps (tasa de usura) and segmenting current banking interest rate methodologies by risk profile to displace informal predatory loans like the infamous gota a gota.
- Open Finance and Regional Friction: Colombia Fintech pushed for a viable technical roadmap for open finance as a stepping stone toward broader open data initiatives. Concurrently, a fierce debate erupted over Bogotá’s proposed hikes to the Industry and Commerce Tax (ICA), which the fintech sector has dubbed an "anti-entrepreneurship" measure.
Chronology of Events and Declarations
The lead-up to and execution of the Latam Fintech Market 2026 marked a critical juncture in the public-private dialogue surrounding Colombia’s financial architecture.
August 31, 2026: Institutional Expansion
The Superintendencia Financiera de Colombia formally authorized Revolut Bank Colombia to operate as a credit establishment. This regulatory milestone injected fresh optimism into the fintech sector, serving as proof that the current government apparatus could accelerate market entry for international digital banking giants.
September 17–18, 2026: The Latam Fintech Market Summit in Barranquilla
Industry leaders, policymakers, and technologists gathered in Barranquilla for the annual summit. Throughout the two-day event, Gabriel Santos outlined Colombia Fintech’s comprehensive legislative and regulatory wishlist. Discussions centered heavily on merging technological efficiency with tax reform.
Post-Summit (September 2026): Media Revelations and Local Tax Battles
In an interview with El Colombiano, Gabriel Santos detailed his "fruitful conversations" with the executive branch regarding the 4×1,000 tax. Simultaneously, friction intensified between the digital economy and municipal authorities as Bogotá’s City Council advanced plans to increase the ICA tariff for financial institutions—triggering immediate pushback from fintech stakeholders concerned about long-term investment incentives.
Supporting Data and Market Realities
The urgency behind Colombia Fintech’s demands is underscored by striking underlying data regarding cash dependency, credit exclusion, and predatory lending practices across the country.
Cash Dependency and MSMEs
Despite rapid strides in digitalization, cash remains king in Colombia:
- 79% of all transactions nationwide are still conducted in cash.
- 82% of micro, small, and medium-sized enterprises (MSMEs) operate primarily or exclusively on cash, limiting their ability to build transparent credit histories.
The Credit Gap and Informal Lending
Access to formal credit remains deeply stratified, leaving millions vulnerable to exploitative informal mechanisms:
- Reports indicate that approximately 63.4% of Colombian adults lack access to credit through formal financial institutions (Portafolio), while other estimates peg the unserved population at around 3 million citizens (El Colombiano).
- This massive credit vacuum feeds the informal lending market, notably the gota a gota (loan shark) networks. During the summit, experts highlighted extortionate informal interest rates reaching up to 382% for individuals and an astonishing 666% for businesses.
Bre-B Transaction Limits
The central bank’s Bre-B platform has successfully stabilized peer-to-peer and peer-to-merchant immediate payments.
- As of 2026, the regulatory ceiling sits at 1,000 Units of Basic Value (UVB), translating to a maximum transaction cap of $12,110,000 COP.
- However, individual financial institutions frequently impose lower internal limits or strict operational caps due to risk management and security protocols, a practice Colombia Fintech wants standardized or dismantled.
Bogotá’s ICA Tax Proposal
The municipal tax debate in Bogotá centers on a shifting tariff scale for financial activities:
- Current Rate: 14 per thousand.
- Proposed 2027 Rate: 20 per thousand.
- Proposed 2028 Rate: 19 per thousand.
- Proposed 2029 Rate: 18 per thousand onwards.
- Note: While the District argues that this tax is calculated on a specialized base rather than total operational revenue and reflects the sector’s ability to pay, fintech leaders warn it deters early-stage tech investment.
Official Responses and Stakeholder Positions
Colombia Fintech: The Push for Structural Competitiveness
Gabriel Santos and the board of Colombia Fintech have maintained that structural reforms are no longer optional if Colombia wishes to modernize its economy.
Regarding the 4×1,000 tax, Santos characterized the levy as an outdated anchor dragging down financial efficiency. While acknowledging that the government shares an interest in tax simplification, Santos stressed that a "gradual and progressive" phase-out is the only sensible path forward. To counter the fiscal shock of losing this revenue, the association advocates for macroeconomic expansion driven by increased competition—arguing that welcoming players like Revolut and streamlining digital rails will naturally broaden the tax base.
On Bre-B, Santos urged authorities to look to global benchmarks like Brazil’s Pix. By removing artificial limits set by banks and integrating state disbursements (such as conditional cash transfers and government payrolls), Bre-B could transform from a basic transfer tool into the backbone of the national digital economy. Furthermore, leveraging merchant payment histories through digital rails could finally provide small businesses with the alternative data needed to secure formal bank loans.
The National Government and Regulatory Bodies
The executive branch has shown an unprecedented willingness to engage in dialogue with tech and financial lobbies. Regulators point to the swift approval of digital banking licenses as evidence of an open-door policy toward innovation.
However, the fiscal reality of the country presents a formidable roadblock. Government officials have yet to present a formal roadmap or fiscal compensation plan to offset the multi-billion-peso hole that eliminating the 4×1,000 tax would instantly create.
Local Government (Bogotá District Administration)
Defending the controversial ICA tax adjustments, the Bogotá District maintains that financial institutions possess a robust capacity to contribute to local public goods and services. Because the tax is applied to a specialized financial base rather than gross operational income, the administration contends that the gradual climb to 20 per thousand in 2027—descending thereafter—is balanced, equitable, and necessary for municipal financing.
Implications for the Future of Colombian Finance
The proposals debated at the Latam Fintech Market 2026 carry profound implications for consumers, traditional banks, and emerging technology firms alike.
1. The Death of Cash and the Rise of Open Finance
If Colombia Fintech successfully lobbies for higher Bre-B caps and the integration of open finance frameworks, the country could rapidly accelerate away from its 79% cash dependency. Standardizing open finance will allow non-bank financial institutions to securely tap into consumer data, offering personalized credit products to populations previously ignored by traditional credit-scoring models.
2. A Balancing Act for Interest Rate Controls
Reforming the methodology for the tasa bancaria corriente and the tasa de usura presents a double-edged sword. While lowering or segmenting rate caps by risk profiles could theoretically inject credit into underserved MSME segments, overly rigid interest rate ceilings risk driving banks away from high-risk borrowers entirely—unknowingly pushing more citizens back into the arms of criminal gota a gota networks.
3. The Fiscal Dilemma
Ultimately, the grand ambitions of Colombia’s fintech sector collide with macro-fiscal constraints. Until a sustainable revenue replacement is found for the 4×1,000 tax, the government’s rhetorical openness to reform will remain stalled by fiscal prudence. For now, the roadmap remains a work in progress, leaving entrepreneurs, bankers, and policymakers to negotiate the delicate balance between rapid digital innovation and fiscal survival.

Leave a Reply