
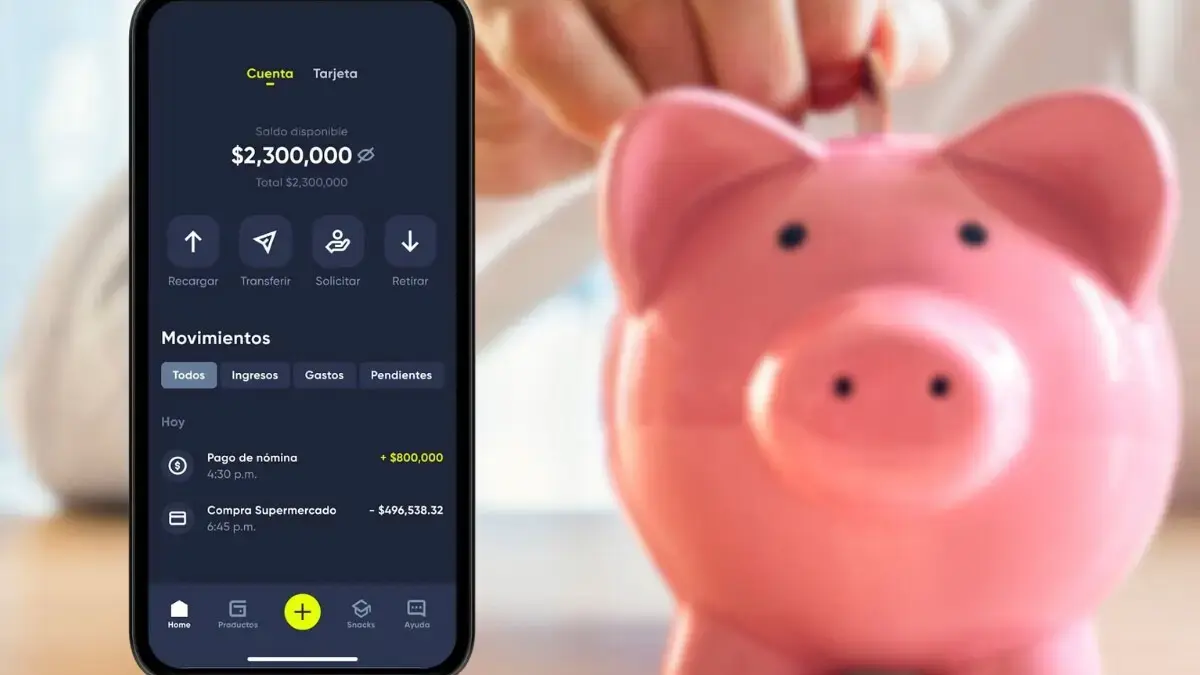
BOGOTÁ, COLOMBIA — In a competitive move designed to attract and retain depositors in an evolving macroeconomic landscape, Lulo Bank has officially elevated the profitability of its digital savings features, known as "Bolsillos" (Pockets). Effective September 10, 2026, customers can now secure effective annual rates (E.A.) of up to 10% on their savings, depending on their user category and the specific savings modality chosen.
This latest adjustment represents a strategic recalibration of Lulo Bank’s product offerings, impacting both flexible savings (Bolsillos Flex) and term-bound savings (Bolsillos Programados). As traditional and digital financial institutions alike navigate fluctuating interest rate environments and persistent inflationary pressures, Lulo Bank’s aggressive yield optimization signals a broader trend in the Colombian neobanking sector: a fierce battle for liquidity centered on high-yield, user-friendly digital tools.
Main Facts
The core of Lulo Bank’s announcement centers on sweeping rate hikes across its ecosystem of digital pockets. Under the new structure, users can achieve returns reaching 10% E.A., a threshold previously reserved for specialized or promotional campaigns, but now institutionalized for specific segments.
Key Highlights of the Rate Restructuring:
- Effective Date: The new interest rates officially came into effect on September 10, 2026.
- Ceiling Rates: The maximum achievable return is now 10% E.A., specifically targeted at users belonging to the Lulo PRO segment.
- Flexible Pockets (Bolsillos Flex): Standard Lulo customers saw their rates jump from 7.50% to 9.50% E.A., while Lulo PRO members experienced an increase from 9.25% to 10% E.A.
- Scheduled Pockets (Bolsillos Programados): For 60-day terms, rates moved from 8% to 9.50% E.A. (standard) and from 9.50% to 10% E.A. (Lulo PRO). For 90-day terms, rates shifted from 8.50% to 9.50% E.A. (standard) and from 9.75% to 10% E.A. (Lulo PRO).
- Macroeconomic Backdrop: The adjustment occurs against an economic backdrop where annual inflation reached 6.24% as of August 2026, giving savers a significantly higher real rate of return (positive real interest rate).
The mechanics of these products remain anchored to the broader Lulo Account ecosystem. Rather than forcing consumers to lock funds away in traditional, bureaucratic Certificate of Deposit (CDT) structures, Lulo Bank’s Bolsillos allow users to compartmentalize their capital digitally within a single main account, combining high yields with operational agility.
Chronology: How Lulo Bank’s Savings Strategy Evolved
To understand the weight of the September 2026 rate adjustments, it is essential to examine the timeline of Lulo Bank’s product rollout and its continuous refinement of digital savings instruments in the Colombian market.
Phase 1: Market Entry and the Introduction of "Bolsillos"
When Lulo Bank launched as one of Colombia’s pioneering 100% digital, federally regulated financial institutions, it faced the dual challenge of building consumer trust and securing low-cost core deposits. To differentiate itself from traditional brick-and-mortar legacy banks, the institution introduced modular savings features.
The initial iterations of Bolsillos were designed primarily for psychological budgeting—allowing users to segregate money for rent, vacations, or emergency funds without opening separate bank accounts. However, as macroeconomic interest rates climbed globally and locally in the post-pandemic years, digital banks realized that algorithmic efficiency alone was insufficient; consumers demanded competitive, compounding yields on every idle peso.
Phase 2: Introduction of Tiered Loyalty (The Lulo PRO Segment)
As the neobank scaled its user base, it introduced the Lulo PRO segment. This tier was engineered to reward primary-account holders—specifically those who routed their salary (nómina) or maintained their primary financial life through the application. By eliminating membership fees for Lulo PRO while attaching perks such as digital payroll loans and specialized insurance products, the bank effectively created a closed-loop ecosystem.
During this phase, rates for Bolsillos hovered in the mid-to-high single digits (typically ranging between 7.50% and 9.25% E.A.). While competitive at the time, softening inflation rates in late 2025 and mid-2026 prompted financial institutions to re-evaluate how aggressively they needed to price liabilities to sustain growth.
Phase 3: The September 2026 Yield Optimization
The announcement on September 10, 2026, marks the most aggressive coordinated rate hike by the institution for its savings pockets. By pushing Lulo PRO yields to the psychological and market milestone of 10% E.A., Lulo Bank has positioned itself at the vanguard of retail banking yields in Colombia.
By simultaneously lifting standard Lulo accounts to 9.50% E.A. on flexible products, the bank has narrowed the gap between basic and premium tiers while maintaining a clear incentive for users to consolidate their financial lives within the Lulo ecosystem.
Supporting Data and Product Mechanics
To fully grasp the implications of Lulo Bank’s offering, one must analyze the granular mechanics governing both Bolsillos Flex and Bolsillos Programados, alongside the macroeconomic data influencing these decisions.
1. Macroeconomic Context: Beating Inflation
According to data cited by Lulo Bank in its official release, Colombia’s annual inflation rate stood at 6.24% in August 2026.
In financial terms, offering a nominal return of 10% E.A. (and a minimum of 9.50% E.A. across these adjusted products) translates to a robust positive real return of roughly 3.26 to 3.76 percentage points. In a historical context where Latin American retail savings accounts frequently suffered from negative real yields—where inflation outpaced nominal interest—Lulo Bank’s product functions as a powerful wealth preservation and accumulation tool for the middle class.
2. Deep Dive: Bolsillos Flex (Flexible Pockets)
- Accessibility: No initial balance requirement is enforced.
- Capacity: Users can open up to 10 Bolsillos Flex simultaneously, enabling hyper-granular categorization of funds.
- Liquidity: Funds can be withdrawn instantly whenever necessary, without financial penalties or loss of accrued yield up to the point of transfer.
- Payout Structure: Yields are calculated based on the average daily balance recorded during the preceding month and are deposited directly into the user’s account during the first few days of each new month.
3. Deep Dive: Bolsillos Programados (Scheduled Pockets)
- Terms: Available in fixed terms of 60 or 90 days.
- Capacity: Users are permitted to maintain up to five Bolsillos Programados concurrently.
- Yield Incentive: Designed for consumers willing to commit capital for a short, defined horizon. Standard users earn 9.50% E.A. at both 60 and 90 days, while Lulo PRO users capture the maximum 10% E.A. threshold.
- Penalty Clause: While funds can technically be withdrawn prior to the expiration of the 60- or 90-day window, doing so strips the user of the special programmed yield. In such cases, the capital reverts to the baseline Lulo account interest structure.
4. The Lulo PRO Advantage
The gateway to the 10% E.A. rate is membership in the Lulo PRO tier. Crucially, this segment does not charge a monthly maintenance or membership fee. Instead, qualification is structural: it targets users who designate Lulo Bank as their primary financial hub—typically through direct deposit of payroll (nómina).
Beyond superior savings yields, the Lulo PRO tier bundles several ancillary financial services:
- Digital Payroll Advances (Libranza Digital): Streamlined, app-based credit options.
- Protected Payroll Insurance (Nómina Protegida): An insurance policy that, subject to specific terms and conditions, can disburse up to $15 million COP to designated beneficiaries in qualifying scenarios.
Official Responses and Strategic Intent
While specific executive soundbites from the C-suite were synthesized directly into the structural adjustments, financial analysts and retail banking experts have widely interpreted Lulo Bank’s September 2026 pivot as a calculated offensive in Colombia’s digital banking wars.
Market observers note that neobanks operating in Latin America’s fourth-largest economy face mounting pressure to demonstrate sustainable unit economics. Relying solely on transactional fee income (such as interchange fees from debit cards) is often insufficient in markets with high cash-preference rates. Therefore, securing stable, sticky, low-cost or medium-cost deposits is paramount.
By incentivizing users to move money into Bolsillos Flex and Programados, Lulo Bank achieves two strategic objectives:
- Asset-Liability Matching: By encouraging 60- and 90-day commitments via Bolsillos Programados, the bank builds a predictable liquidity curve that supports its lending operations (such as digital loans and mortgages).
- Ecosystem Lock-in: Offering a 10% E.A. return exclusively to Lulo PRO members creates high switching costs. A consumer earning double-digit returns on their savings while enjoying fee-free payroll processing is statistically far less likely to churn to a competing fintech or traditional financial institution.
Furthermore, representatives for the bank have emphasized that all announced percentages reflect current market conditions as of September 10, 2026, leaving open the possibility of future calibrations should the broader monetary policy rate set by Banco de la República (Colombia’s central bank) undergo further transformation.
Implications for Consumers and the Colombian Financial Landscape
The decision by Lulo Bank to elevate its savings yields to 10% E.A. ripples across multiple layers of the Colombian financial ecosystem, carrying distinct implications for everyday depositors, competing neobanks, and traditional legacy institutions.
For the Everyday Saver
For retail consumers, the normalization of 10% E.A. digital yields democratizes access to institutional-grade returns. Historically, earning double-digit nominal returns required locking away significant capital in traditional, inflexible Bank CDs for terms of one year or longer, often accompanied by complex paperwork and maintenance fees.
Lulo Bank’s model shatters these barriers. A user can manage up to 10 flexible pockets from their smartphone, withdraw funds instantly for emergencies, and still capture a 9.50% to 10% E.A. return. For households battered by historical inflation spikes, this product design provides both the liquidity required for day-to-day survival and the yield necessary to outpace the devaluation of purchasing power.
For Competing Fintechs and Neobanks
Colombia’s neobanking sector—featuring players like RappiPay, Nu Colombia, and various digital spinoffs of traditional banks—is locked in an intense battle for market share. When one major digital institution adjusts its savings rates upward, competitors are forced to respond to prevent capital flight.
The September 2026 adjustment by Lulo Bank raises the bar for digital deposit acquisition. Competitors that fail to offer competitive yields on flexible savings risk losing their most active depositors. Consequently, consumers can expect a hyper-competitive savings market characterized by aggressive promotional rates and innovative pocket-based budgeting tools.
For Traditional Legacy Banks
Traditional banks in Colombia, long accustomed to maintaining low-yield, high-fee traditional savings accounts, face an accelerating erosion of low-cost retail deposits. As tech-savvy consumers migrate their payrolls and emergency funds to regulated digital institutions like Lulo Bank to capture 10% E.A. returns, legacy institutions are forced into a defensive posture—either digitizing their own savings offerings or watching their core deposit base evaporate.
Conclusion
Lulo Bank’s decision to elevate its Bolsillos Flex and Programados rates to up to 10% E.A. as of September 10, 2026, is far more than a routine minor rate adjustment. It is a strategic statement of intent in a maturing digital financial market. By successfully combining high yields, real positive returns against an inflation rate of 6.24%, absolute liquidity through flexible pockets, and targeted loyalty incentives via the Lulo PRO segment, Lulo Bank has reinforced its position as a formidable leader in Colombia’s fintech revolution. As market dynamics continue to shift, the ultimate beneficiaries of this intense corporate competition will be Colombian consumers, who now enjoy unprecedented access to high-yield, flexible, and digital-first wealth management tools.

Leave a Reply