
BOGOTÁ — The landscape of Colombian digital banking is entering a transformative new era. For years, the market has proven that consumers possess a voracious appetite for financial products managed entirely from the convenience of a smartphone application. The initial hurdle—convincing a historically cash-dependent population to trust digital platforms—has been cleared. Now, the market has evolved into a sophisticated arena where users demand diverse options for saving, credit acquisition, domestic movement of funds, and, increasingly, seamless cross-border financial operations.
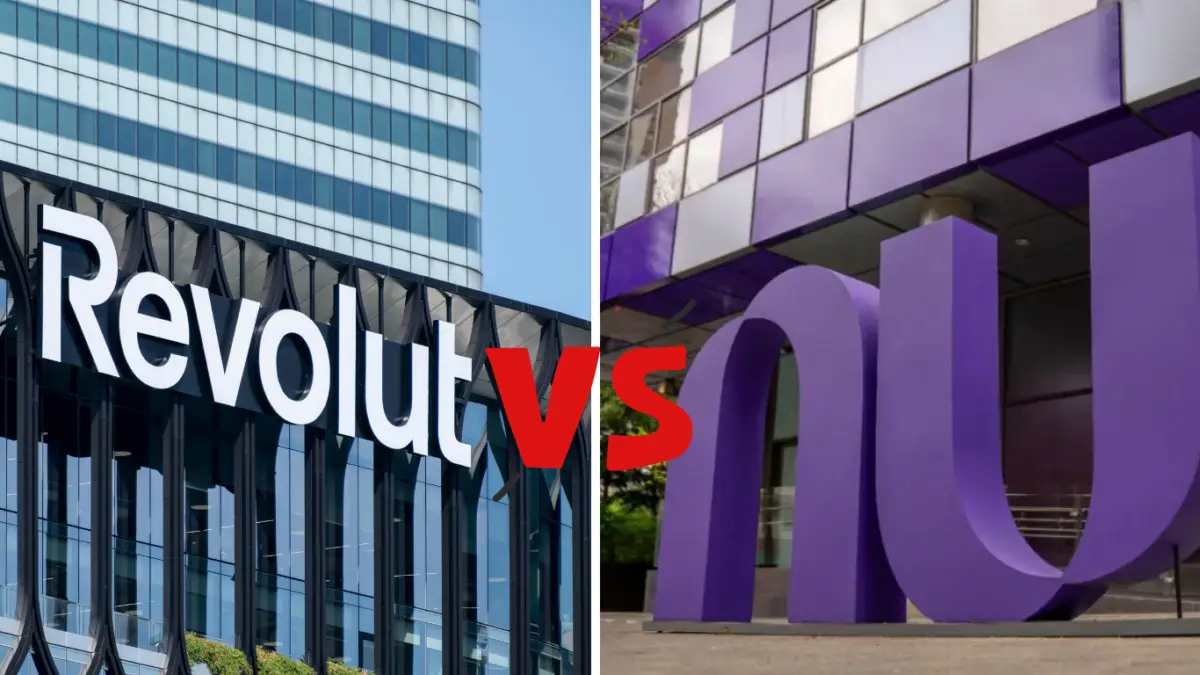
Into this fertile and fiercely contested ecosystem steps Revolut, one of the world’s most prominent fintech giants. Armed with a newly minted operating license from the Superintendencia Financiera de Colombia (the country’s financial watchdog) and a substantial local investment, the European heavyweight is poised to disrupt the status quo. However, it arrives not as a pioneer blazing a lonely trail, but as a challenger to established digital juggernauts—most notably, Nu (Nubank), which has spent the last half-decade cementing its dominance across the Colombian market.
The impending clash between Revolut and Nu represents much more than a corporate rivalry; it is a bellwether for the future of Latin American fintech. As both institutions position themselves to capture the everyday financial lives of millions, the Colombian consumer stands to benefit from unprecedented innovation, aggressive pricing, and borderless banking solutions.
1. Main Facts: Revolut’s Colombian Offensive and the Nu Precedent
The arrival of Revolut in Colombia is anchored by monumental figures and strategic maneuvers. Officially greenlit by the Superintendencia Financiera to operate as a fully fledged financial institution, Revolut aims to officially roll out its consumer operations by 2027. To build the necessary foundational strength, the company has pledged an additional $62 million in localized infrastructure investment. Long before its official launch, the brand’s gravity has pulled nearly 200,000 eager Colombians onto its domestic waitlist.
Revolut enters the market boasting a global footprint of over 80 million clients, leveraging a wealth of international experience across diverse regulatory and economic landscapes. Yet, scale alone does not guarantee local victory. The fintech must contend with a sophisticated consumer base and entrenched competitors who intimately understand the macroeconomic and cultural nuances of Colombia.
Chief among these competitors is Nu. Arriving in Colombia years earlier with a focused, minimalist value proposition—a credit card devoid of physical branches and managed exclusively through a mobile app—Nu has undergone a dramatic scaling process. Five years into its Colombian journey, Nu boasts a staggering five million clients within the country. Its balance sheet reflects massive local adoption, anchored by over COP $10 trillion in total deposits spanning traditional savings accounts and Certificates of Deposit (CDTs). Nu’s product portfolio has systematically expanded to encompass credit cards, high-yield savings accounts, term deposits, and personal loans, evolving from a monoline credit card issuer into a comprehensive financial ecosystem.
2. Chronology of the Fintech Surge in Colombia
Understanding the current high-stakes rivalry requires tracing the rapid evolution of Colombia’s digital financial sector over the past several years:
- 2019–2020 (The Genesis of Digital Credit): Nu and other early digital challengers establish a foothold in Colombia, primarily introducing credit cards with transparent, fee-free digital management to an underserved demographic accustomed to traditional banking red tape.
- 2021–2022 (The Savings and Deposit Boom): Regulatory updates and shifting consumer habits during and immediately after the pandemic spark a rush toward digital savings accounts. Fintechs introduce high-yield daily liquidity products, fundamentally altering how Colombians view interest-bearing accounts.
- September 10 (Nu Global Announcement): In a strategic preemptive move, Nu unveils Nu Global, an ambitious initiative designed to bridge the financial lives of individuals living across multiple countries. Initially connecting more than 35 markets throughout Latin America and Europe, the platform signals Nu’s intent to break out of domestic silos.
- Mid-September (Revolut’s Regulatory Milestone): Just five days after Nu’s global cross-border announcement, Revolut officially confirms its acquisition of a banking license in Colombia, signaling the start of a direct, international-versus-regional slugfest.
- 2027 (Projected Launch): Revolut prepares for its official commercial rollout in Colombia, following a multi-year infrastructure development phase backed by its $62 million investment.
3. Supporting Data and Product Ecosystems
To fully comprehend the battlefield, one must analyze the specific weaponry both fintechs bring to the table in terms of rates, products, and geographic utility.
Nu’s Local Fortress
Nu has successfully anchored its user base through aggressive, transparent yields. Its flagship Cuenta Nu offers a compelling 9.30% Effective Annual (EA) return via its automated savings pockets known as Cajitas. Coupled with free, instantaneous transfers to other financial institutions and absolute liquidity (funds are accessible 24/7 without lock-in penalties), Nu has effectively forced traditional banks and competing fintechs to rewrite their value propositions, moving the competitive metric far beyond the simple absence of management fees.
Revolut’s Multicurrency Arsenal
While Revolut has yet to publicly disclose its definitive local fee schedules, interest rates, or credit limits for the Colombian market—keeping ultimate comparative judgments on hold—its global product roadmap hints at a fundamentally different value proposition. Revolut’s crown jewel is its multi-currency account infrastructure, designed to support savings and transactions across 31 different fiat currencies.
Furthermore, Revolut’s ecosystem extends deep into global investment products, granting mobile app users seamless access to international equities, Exchange-Traded Funds (ETFs), and alternative digital assets. Its rewards programs are equally ambitious, featuring localized perks where cash-back and loyalty miles can be earned even through standard debit card transactions.
| Feature / Metric | Nu (Nubank Colombia) | Revolut (Colombia Market Entry) |
|---|---|---|
| Current Local Status | Operational, 5+ years in market | Licensed, commercial launch projected for 2027 |
| Local Client Base | 5 million+ customers | ~200,000 on pre-launch waitlist |
| Local Deposits | Over COP $10 trillion (Savings & CDTs) | Developing infrastructure ($62M investment) |
| Savings Yield | 9.30% EA (Cajitas) | To be announced |
| Core Differentiator | Deep local market penetration & high-yield daily savings | Global multi-currency accounts (31 currencies) & international investing |
| Global Footprint | Dominant across Brazil, Mexico, and Colombia | 80 million+ clients worldwide |
4. Official Responses and Strategic Vision
Leadership on both sides has articulated visions that highlight distinct corporate philosophies regarding growth, market capture, and consumer relationships.
Diego Caicedo, CEO of Revolut in Colombia, has struck an ambitious tone regarding the company’s impending market entry. In preliminary statements, Caicedo has anticipated a disruptive product suite built around aggressive savings yields and flexible credit structures. He has asserted that Revolut’s upcoming rates will rank among the most competitive in the Colombian market. However, fintech analysts and consumers alike maintain a cautious posture, emphasizing that these claims must be verified once formal price lists, interest structures, and credit policies are publicly unveiled.
Conversely, executives at Nu emphasize their deep, organic integration into the daily economic life of the average Colombian. Rather than leaning purely on global prestige, Nu’s leadership points to the more than COP $10 trillion in deposits as definitive proof of localized trust. Their strategic focus remains centered on expanding domestic financial inclusion while simultaneously building regional and global corridors—exemplified by Nu Global—to serve the increasingly internationalized modern professional.
5. Market Implications: The Battle for the Primary Account
The arrival of Revolut and the simultaneous expansion of Nu carry profound implications for the broader Colombian financial sector. The competition between these two digital giants will ultimately be decided not by flashy sign-up bonuses or temporary high-yield promotions, but by a holy grail of modern banking: becoming the user’s primary financial account.
Beyond the Secondary App Syndrome
Historically, many digital banking consumers in Latin America engage in "app-hopping"—maintaining multiple digital wallets and fintech accounts solely to chase short-term high interest rates or to execute specific, isolated transactions. The true financial battleground lies in moving past this behavior.
Achieving primary account status means convincing an individual to deposit their primary salary, automate their utility bill payments, utilize the platform’s proprietary debit and credit cards for daily commerce, maintain long-term savings, secure personal loans, and execute international remittances all within a single ecosystem. Accomplishing this requires building a profound, high-trust relationship that spans the entirety of a consumer’s financial existence.
The Fragmented Target Audience
The clash between Revolut and Nu introduces a fascinating demographic divergence:
- The Global Citizen: Revolut’s value proposition—featuring multi-currency holdings, international remittances, foreign investments, and cross-border perks—resonates powerfully with a specific, highly mobile segment of the population. Digital nomads, remote workers employed by foreign corporations, frequent international travelers, students studying abroad, and freelancers receiving payments in foreign currencies will find Revolut’s architecture uniquely suited to their lifestyles. For this audience, the utility of a borderless account outweighs minor fractional differences in local savings yields.
- The Domestic Mainstream: Nu, meanwhile, has mastered the art of capturing the broader domestic consumer. By focusing on intuitive credit access, transparent everyday banking, and robust local yields like its Cajitas, Nu has successfully integrated itself into the financial routines of millions of everyday Colombians who operate primarily within the national economy.
The Ultimate Winner: The Colombian Consumer
As Revolut finalizes its infrastructural rollout toward its 2027 debut and Nu scales its cross-border capabilities through initiatives like Nu Global, the traditional Colombian banking sector faces unrelenting competitive pressure. Legacy institutions are being forced to accelerate their own digital transformations, strip away predatory hidden fees, and modernize their user interfaces to avoid losing market share to agile, tech-first competitors.
For the end user, the outcome is unequivocally positive. The rivalry guarantees a continuous influx of innovative products, greater pricing transparency, and a fundamental shift in how financial services are delivered. As these two digital titans vie for dominance—one leveraging deep local roots, the other wielding unmatched global infrastructure—the Colombian consumer stands to inherit a modern, flexible, and truly borderless financial future.

Leave a Reply